
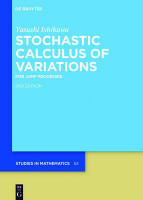
Stochastic Calculus of Variations(English, Hardcover, Ishikawa Yasushi) Offer
Lowest Price
2999

- Language: English
- Binding: Hardcover
- Publisher: De Gruyter
- Genre: Mathematics
- ISBN: 9783110377767, 9783110377767
- Pages: 288
In Stock
FREE
Stochastic Calculus of Variations Price In Online India

Stochastic Calculus of Variations Price Comparison In Online India
Store
Price
Buy at Store


Stochastic Calculus of Variations Specifications
Product Features:
Stochastic Calculus of Variations Features & Specifications stand apart in the PBWL : Stochastics category. The details about Stochastic Calculus of Variations(English, Hardcover, Ishikawa Yasushi) are given below as well. Unboxing Stochastic Calculus of Variations specs Language: English, Binding: Hardcover, Publisher: De Gruyter, Genre: Mathematics, ISBN: 9783110377767, 9783110377767, Pages: 288, & more details are given below
This monograph is a concise introduction to the stochastic calculus of variations (also known as Malliavin calculus) for processes with jumps. It is written for researchers and graduate students who are interested in Malliavin calculus for jump processes. In this book "processes with jumps" includes both pure jump processes and jump-diffusions. The author provides many results on this topic in a self-contained way; this also applies to stochastic differential equations (SDEs) "with jumps".The book also contains some applications of the stochastic calculus for processes with jumps to the control theory and mathematical finance. Namely, asymptotic expansions functionals related with financial assets of jump-diffusion are provided based on the theory of asymptotic expansion on the Wiener-Poisson space. Solving the Hamilton-Jacobi-Bellman (HJB) equation of integro-differential type is related with solving the classical Merton problem and the Ramsey theory.The field of jump processes is nowadays quite wide-ranging, from the Levy processes to SDEs with jumps. Recent developments in stochastic analysis have enabled us to express various results in a compact form. Up to now, these topics were rarely discussed in a monograph. Contents:PrefacePreface to the second editionIntroductionLevy processes and Ito calculusPerturbations and properties of the probability lawAnalysis of Wiener-Poisson functionalsApplicationsAppendixBibliographyList of symbolsIndex
Even though Flipkart offers wide range of PBWL : Stochastics in comparison to Stochastic Calculus of Variations. This Stochastic Calculus of Variations deal is the cheapest you can purchase in Online online. We have also included an Unboxing video of Stochastic Calculus of Variations as well as video review. Stochastic Calculus of Variations is ideal for gifting Men & Women. Multiple Stochastic Calculus of Variations color options might also be available Online or in local store in Online be sure to check them before placing final order online. Exchange offers, Bulk discount, Special price, Promo Code, Coupon code, Cashback might also be applicable on Stochastic Calculus of Variations
Stochastic Calculus of Variations Specs
Book Details
| Imprint | De Gruyter |
Dimensions
| Height | 240 mm |
| Length | 170 mm |
| Weight | 630 gr |
Books Info
| Language | English |
| Binding | Hardcover |
| Pages | 288 |
| Publisher | De Gruyter |
| Year | 0 |
| Author | Ishikawa Yasushi |
Stochastic Calculus of Variations Rating:
4.90
Average RatingShare your experience and Rate Stochastic Calculus of Variations
Disclaimer: